IN Brief:
- TSL led the September contractor table on an Agratas package estimated at £280m by Barbour ABI; the official sum is undisclosed.
- Winvic placed second and Willmott Dixon third, with the latter moving into first position over 12 months.
- The top 50 contractors won £3.14bn across 110 projects, compared with £3.12bn across 126 in August.
TSL led the UK construction contractor rankings for September 2026 after Barbour ABI attributed an estimated £280 million of work to its appointment at the Agratas battery manufacturing development in Somerset. Winvic placed second and Willmott Dixon third, while the leading 50 contractors recorded £3.14 billion of awards across 110 projects. August’s equivalent total was £3.12 billion across 126 projects, making the latest monthly increase in value small despite a reduction of 16 in the number of schemes.
With fewer recorded projects accounting for a slightly greater total, the September table reflects a concentration of award value in some large schemes, particularly industrial construction and logistics. The figures describe contracts added to Barbour ABI’s intelligence records during the reporting period, rather than construction completed or money received by contractors. An appointment can also enter such a ranking after the change in delivery arrangements has become public, particularly when the assigned package value is an estimate rather than a disclosed contract sum.
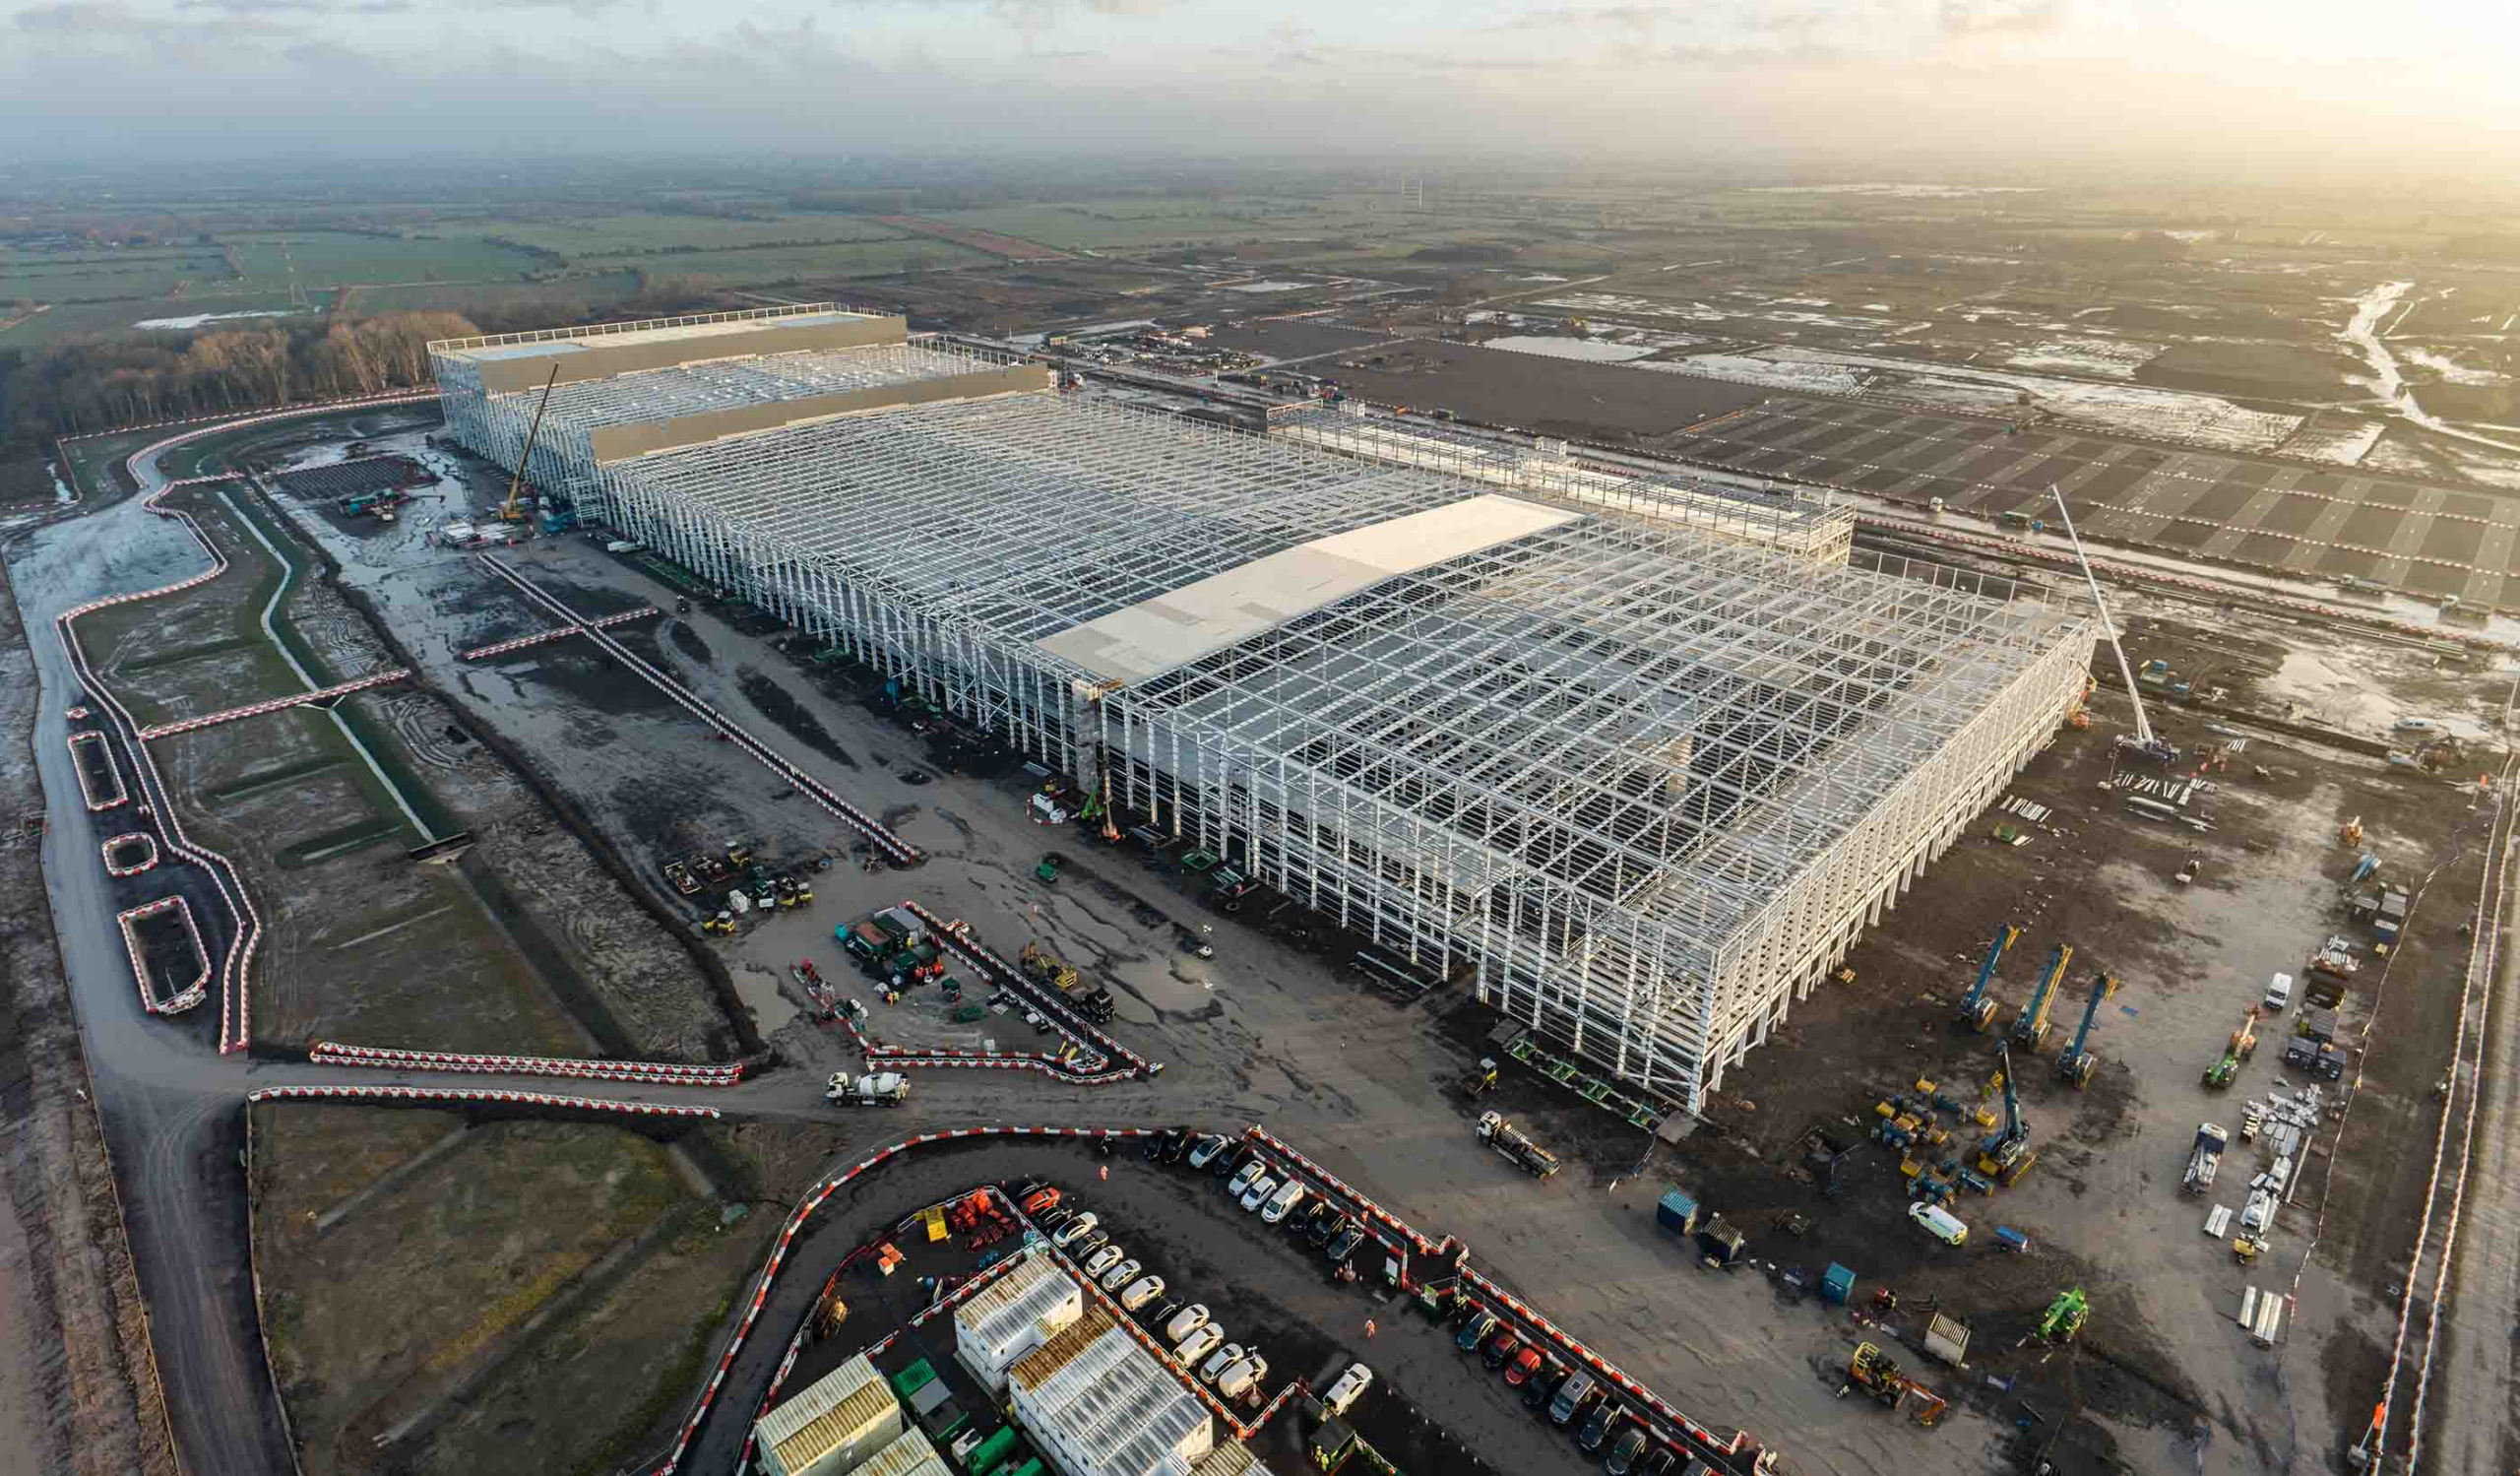
At the Gravity Smart Campus near Bridgwater, Agratas is developing a battery cell manufacturing facility whose main production structures must ultimately accommodate permanent utility services and specialist production equipment. TSL’s position in the ranking follows the earlier replacement of Sir Robert McAlpine as a principal construction partner. The contractor change preceded the September award ranking, which records the value assigned to TSL’s subsequent package.
Barbour ABI’s valuation of £280 million relates to the TSL package recorded in its table, but Agratas has not published an official sum for the appointment. The figure remains a market intelligence estimate, with no basis for presenting it as the total cost of the Somerset factory or the price of every subsequent package. Agratas’s wider development involves separate building, infrastructure and manufacturing investments beyond the particular work represented in the contractor ranking.
Before TSL’s appointment was reflected in the September rankings, Agratas had already completed the steel frame of Building One, as confirmed in February 2026. The structure measures approximately 525 metres long, 167 metres wide and up to 34 metres high. Later updates described external cladding work and progress on a central utilities building, which will supply services needed for the manufacturing operations when the production equipment is installed.
As the structural shell and envelope advance, utility connections and internal service distribution must be coordinated with the space reserved for process equipment. Routes for electrical infrastructure and other services affect plant placement, access and the sequence in which installation teams can work inside the building. Agratas has not published a scope breakdown showing how those activities are allocated to the estimated £280 million TSL package, preventing a reliable assignment of individual engineering works to that figure.
The industrial and logistics emphasis extended beyond Somerset, with Winvic taking second place after awards associated with Tritax Big Box and SEGRO at Symmetry Park and Northampton Gateway. Large distribution schemes typically involve loading yards, access roads and drainage as well as the building structure, so construction activity must be organised around both internal storage operations and the movement of heavy goods vehicles. The available September award information does not establish a common foundation type or building services specification for those individual projects.
External works can account for a substantial part of warehouse delivery, especially where freight circulation, hardstanding and connections to existing highways have to be provided before occupation. Those requirements help explain why a recorded logistics package may extend beyond steel framing and cladding, although the allocation and value of such work can differ considerably between developments. The balance between building structures and external infrastructure will depend on the scope of each awarded Winvic scheme.
Willmott Dixon ranked third for September after securing £183 million in recorded awards, while its accumulated work moved it to the top of the rolling 12-month table ahead of Kier. The two league positions describe different periods: the monthly ranking captures recent recorded awards, whereas the annual measure aggregates qualifying contracts over a year. A contractor can therefore lead the longer comparison without having secured the largest package during September itself.
Barbour ABI’s published comparisons are based on recorded construction awards, with framework appointments excluded from the project values used to rank contractors. A framework can provide access to future commissions across several years, while individual awards enter the rankings when a qualifying construction contract is recorded.
A development involving several delivery phases can also generate overlapping contract records when principal contractors change, making the scope attributed to a particular award important. For Agratas, the £280 million remains Barbour ABI’s valuation rather than a number confirmed by the project developer. The monthly ranking consequently identifies TSL’s recorded leading position without resolving the contract’s undisclosed commercial terms.
September’s top 50 total rose by just £20 million while its project count fell by 16, within the portion of the UK market captured by the dataset. Later tables will show whether that concentration in larger awards persists; progress on the factory and logistics schemes will meanwhile emerge through separate construction milestones rather than through the contract rankings themselves.